

CoverMe - Instant Cash Advance
DIONIS K
- 4.6
- 2.11K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
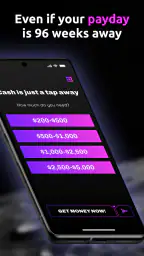
CoverMe - Instant Cash Advance Pros and Cons
Pros
- Fast application process with minimal paperwork
- Clear repayment schedule shown before accepting an advance
- Useful for handling unexpected short-term expenses
- Secure login options help protect account access
- Funds can arrive quickly when eligibility requirements are met
Cons
- Advance limits may be too low for larger financial emergencies
- Fees or optional tips can increase the total repayment amount
- Eligibility and approval are not guaranteed for every applicant
- Repayment dates may be difficult to change after receiving funds
- Availability and terms can vary by state and user profile
 Analysis by All-app
When an unexpected bill lands before payday, the hard part is often not deciding that you need help; it is finding an option that matches the timing of your income. CoverMe - Instant Cash Advance is a free finance app from DIONIS K built around that exact moment. I approached it as a short-term cash tool rather than a complete money-management system, and that distinction matters from the first screen.
The app’s central promise is unusual for this category: it presents itself as useful even when payday is far away, with the store summary mentioning a gap of up to 96 weeks. That makes it sound more flexible than a typical payday-style advance, but I would still treat the wording as an invitation to examine the actual offer carefully rather than as a reason to borrow automatically. A longer repayment horizon can reduce immediate pressure while potentially making the overall commitment more important to understand.
In everyday terms, I see this app fitting a narrow but real situation: a necessary expense arrives, waiting is not practical, and I need to investigate a cash option quickly. It is not the app I would open for budgeting, investing, building savings, or tracking every household transaction. Its value is concentrated around the borrowing decision and the path from financial need to possible cash access.
From an urgent expense to a borrowing decision
My first step with a finance app like this is to define the problem before touching the application. If the issue is a recurring shortage, an advance only moves the pressure forward. If it is a one-off repair, a medical-related expense, or another unavoidable bill, a short-term option may be easier to evaluate. CoverMe is more useful when I already know the amount I am trying to cover and when I can explain how repayment would fit into my next income cycle.
The free price removes one obvious barrier to trying the app, and the Everyone content rating makes it broadly approachable from an app-store perspective. That does not make borrowing risk-free. The important questions begin after installation: what information is requested, what offer is presented, what repayment terms apply, and whether the final amount fits my budget. I would not confuse access to the application with approval for funds.
The app is currently listed as version 1.6.3 and supports Android 7.0 or later. That is helpful for people using an older Android phone, although compatibility does not tell me whether the service will suit every financial situation. I would also update the app before starting an application, because a finance workflow is a poor place to rely on an outdated build if a newer one is available.
What I would prepare before starting
A smoother application begins outside the app. I would have a clear figure in mind, check the date and size of my next reliable income, and list the bills that must be paid before repayment becomes due. This small preparation is one of the most useful habits with CoverMe because it prevents the urgency of the moment from deciding the amount for me.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I would also separate “needed now” from “nice to have.” If I need a smaller advance than the maximum that might be offered, taking only the smaller amount can reduce the repayment burden. That sounds obvious, but fast-cash interfaces can encourage people to focus on what is available instead of what is affordable. My rule would be to use the app as a calculator for a specific gap, not as extra spending power.
Another practical step is to read each screen slowly, especially where the app moves from general information to a personalized offer. A preliminary request and a completed borrowing agreement are not the same thing. I would look for the total repayment, timing, any applicable charges, and what happens if my expected income arrives late. If those details are not clear enough to compare, I would stop rather than continue out of impatience.
The application flow and its handoffs
The main workflow is best understood as a series of handoffs. I begin with my financial need, then provide the information required for the app to assess or route the request, then review the result, and finally decide whether to accept the terms. The app can make the first part convenient, but the responsibility changes hands at every stage: from my estimate, to the information I submit, to the offer shown, and eventually to the repayment obligation.
That handoff is where I would pay closest attention. A broad statement about getting cash is not the same as a guarantee that every user will receive money, receive the amount requested, or receive it on the same timetable. The outcome depends on the individual application path and the terms presented to that person. I would therefore judge CoverMe by the clarity of that transition, not just by how quickly the opening screen gets me started.
There is also a psychological handoff between urgency and commitment. At the beginning, I may be thinking, “I need to solve this bill.” By the time an offer appears, I need to switch to, “What exactly am I agreeing to, and how will this affect the next several weeks?” That change in mindset is essential. A polished or simple interface should not replace a careful reading of the agreement.
For a realistic example, imagine that my phone breaks shortly before an important work shift and I need a repair immediately. I would first estimate the repair amount, open CoverMe, and follow the request process. If the resulting terms show a repayment schedule that leaves enough room for rent, food, transport, and existing commitments, I might consider it. If the repayment consumes the money I need for essentials, the correct result is to decline, even if the application itself is fast and easy.
Why the longer-payday angle changes the comparison
Traditional payday advances are usually associated with a short window tied closely to the next paycheck. CoverMe positions itself differently by addressing situations where payday may be much farther away. That can be appealing to someone whose income schedule is irregular or whose next expected payment is not close enough for a conventional advance to be practical.
However, a longer period is not automatically a better deal. It can make a repayment amount feel manageable while extending the financial obligation. When I compare this app with a bank overdraft, a credit-union option, a credit card, or help from a trusted person, I would compare the complete cost and timing rather than simply asking which option delivers money fastest.
A bank or credit union may be a better choice for someone with an established relationship, predictable income, and time to wait for a more conventional decision. A credit card may offer flexibility for a person who can repay quickly and already understands its terms. A payment plan with the bill provider may avoid borrowing altogether. CoverMe becomes more interesting when those alternatives are unavailable, too slow, or unsuitable, but that does not make it the best option by default.
The non-obvious trade-off is that the app’s appeal may increase precisely when my financial position is least comfortable. The farther payday is away, the more important it becomes to test whether repayment is realistic. I would use the longer-payday concept to widen the comparison, not to lower my standards.
What happens after the request
Once the request reaches the point where an offer or decision is presented, I would slow down again. I want to know the amount I would receive, the amount I would repay, the dates involved, and whether accepting creates a commitment that is difficult to change. I would save or record those details for my own budget before accepting, because relying on memory is risky when the decision is made under pressure.
This is also the point where a user may wonder whether the app itself is the lender, a matching service, or part of a broader process. I would not assume the role from the app’s name or category. The relevant answer is found in the terms and disclosures shown during the application. That distinction affects who handles the agreement, who sends the funds, and who receives repayment, so it deserves attention before the final confirmation.
In practical use, I would treat every external transition as a checkpoint. If the app sends me to another service, asks me to review a separate agreement, or changes the amount or timing from what I expected, I would read that new step independently. A handoff can be legitimate and still require fresh scrutiny. The safest workflow is not the one with the fewest taps; it is the one where I understand what each tap changes.
I would also avoid beginning the process while distracted or on a poor connection. A partially completed financial request can create confusion about what was submitted and what still needs action. Before closing the app, I would make sure I know whether the request is incomplete, pending, approved, or declined, and I would keep any confirmation information available for my records.
The result I would consider successful
For me, a successful outcome is not simply money arriving. It is a clear, affordable resolution to a specific problem, with no surprise in the repayment schedule and no need to borrow again to cover the first advance. That definition makes CoverMe more useful as a decision tool than as an emergency button.
If the request produces terms I can afford and the money addresses a genuine shortfall, the app may provide practical relief. The free download and focused purpose make it easy to investigate without committing immediately. Its broad adoption is also notable: it has passed 100 thousand installs, carries a 4.6 average from around 32 thousand ratings, and has about 2.1 thousand written reviews. Those figures suggest that many people have found the app worth trying, although popularity cannot tell me whether a particular offer is suitable for my circumstances.
I would measure the result over the entire repayment period. Did the advance solve the original expense without causing a second shortage? Did I understand the timing correctly? Did I have enough room for ordinary bills? These questions matter more than the speed of the initial application. A cash advance that fixes today but destabilizes next month is not a strong financial outcome.
One useful workflow is to write the repayment date beside the original bill in my calendar and reserve the relevant amount as soon as income arrives. I would not wait until the due date to discover that other expenses have consumed the money. This simple separation turns the app’s result into a planned obligation instead of an invisible future deduction.
Where the flow breaks down
The biggest weakness is inherent to the product category: convenience can encourage rushed borrowing. CoverMe may help me reach a possible cash solution, but it cannot remove the underlying cost of being short on money. If I am already juggling several repayments, have uncertain income, or need repeated advances to cover essentials, I would skip this app and seek debt advice, a hardship arrangement, or a lower-cost alternative.
The workflow can also break when the user expects a guaranteed amount or instant certainty. The store summary is attention-grabbing, but real financial decisions involve eligibility, individual terms, and timing. I would be uncomfortable proceeding if the app’s language felt more definite than the agreement itself. The correct response to an unclear offer is to pause, not to assume the most favorable interpretation.
Another friction point is comparison. A fast application can make other options feel inconvenient, even when they may cost less. Before accepting, I would spend a few minutes checking whether the bill provider offers an extension, whether my bank has a suitable overdraft arrangement, or whether a credit union can provide a more manageable product. That extra step is especially important when the proposed repayment extends well beyond the next payday.
I would also skip CoverMe if my need is not urgent. For planned purchases, building a small savings buffer or waiting until I can pay directly is usually cleaner than creating a new obligation. Likewise, someone looking for detailed spending insights, automated budgeting, or long-term financial planning should choose a dedicated personal-finance app instead. CoverMe’s strength is its narrow focus, and that is also its boundary.
Who should use it, and who should be cautious
I think the app is best suited to an adult who has a defined short-term cash gap, understands that an advance must be repaid, and is willing to inspect the full terms before accepting. It may be particularly relevant when the next income date is not close enough for a conventional payday product, provided the eventual repayment plan remains realistic.
I would be more cautious if my income changes from week to week, if an existing debt already takes a large share of my budget, or if I am using borrowing for groceries and utilities repeatedly. In those cases, the app may address the immediate symptom while leaving the larger problem untouched. A conversation with the creditor, employer, bank, or a nonprofit advice service could be more useful than another advance.
Age suitability also deserves a practical interpretation. The Everyone rating describes the app’s store classification, not a promise that borrowing is appropriate for every person who can install it. I would make the decision based on legal eligibility, personal income, and the agreement’s requirements, rather than on the content label alone.
My practical verdict after following the workflow
CoverMe is a focused finance app for investigating cash advances when ordinary payday timing does not match the user’s situation. I like the way its purpose is easy to understand, and the possibility of dealing with a distant payday gives it a different place in the comparison than a standard next-paycheck product. The free access also makes it straightforward to review the process before deciding.
My reservation is equally clear: the app’s usefulness depends almost entirely on the terms shown for the individual request. I would never accept because the application feels quick, because the amount is available, or because the repayment period sounds comfortable in isolation. I would accept only when the total obligation, schedule, and effect on my essential spending all make sense together.
Developed by DIONIS K and listed for Android users on version 1.6.3, it has attracted a substantial audience while remaining a very specific tool rather than a full financial companion. My recommendation is to use CoverMe as a careful comparison step, not as a default rescue plan. Open it with a fixed need, move through each handoff deliberately, record the final terms, and walk away when the result would create a larger problem than the bill that brought you there.
Frequently Asked Questions
What is CoverMe - Instant Cash Advance?
CoverMe - Instant Cash Advance is a financial app designed to help eligible users request short-term cash advances through a mobile device. It may provide access to funds before the next payday, depending on the information submitted, account status, and applicable eligibility requirements. Before using it, review the available advance amount, repayment schedule, service charges, and any other terms shown in the app.
How does CoverMe determine whether I am eligible?
Eligibility can depend on several factors, including your identity, income, employment or deposit history, banking information, and activity within the service. Meeting the basic requirements does not necessarily guarantee approval or a specific advance amount. CoverMe may also request permission to verify information through connected accounts. Users should provide accurate details and carefully read the approval conditions before accepting an offer.
Are there fees or other costs associated with CoverMe?
The total cost of using CoverMe depends on the advance terms presented to you. Possible costs can include subscription charges, express-transfer fees, optional services, or other applicable fees, while the exact structure may vary by location and user account. Do not assume that an advance is free simply because it does not use traditional interest. Check the fee breakdown, recurring charges, and cancellation rules before confirming.
How and when do I repay a CoverMe cash advance?
Repayment is generally scheduled according to the date and terms displayed when the advance is accepted. CoverMe may collect the amount from a linked bank account or another authorized payment method, so users should make sure sufficient funds are available. Missing a payment could lead to additional charges, failed-payment consequences, or account restrictions. Always review the repayment date and contact support if your circumstances change.
Is CoverMe safe to use, and what information does it require?
As a financial service, CoverMe may request sensitive information such as your name, contact details, identity documents, income information, and bank-account data. Download the app only from an official store, verify the publisher, and review its privacy policy and requested permissions. Use a secure device and avoid sharing login codes. Remember that no financial app can guarantee approval, instant delivery, or complete protection from fraud.


